What’s changed: Updated 24 September 2026: rewritten for the 4.35% rate, with every comparison re-run against today’s savings rates. Earlier, 5 September: the first draw at 4.35% paid 6,529,868 prizes. Full update history.
Educational, not advice. This article explains the Premium Bonds prize fund rate and compares it with other savings products. Savvy Investor Guide is not authorised or regulated by the Financial Conduct Authority. Nothing here is personal financial advice; where you hold your savings depends on your circumstances, your tax position and your goals.
What this article covers: the rise in the Premium Bonds prize fund rate to 4.35% from the September 2026 draw, what that rate does and does not mean for one saver, how Premium Bonds compare with the best easy-access, fixed-rate and cash ISA accounts as at 24 September 2026, who the product suits at this rate, and the mechanics.
What it does not cover: whether you personally should hold or sell Premium Bonds, or tax planning for high-income or non-resident savers.
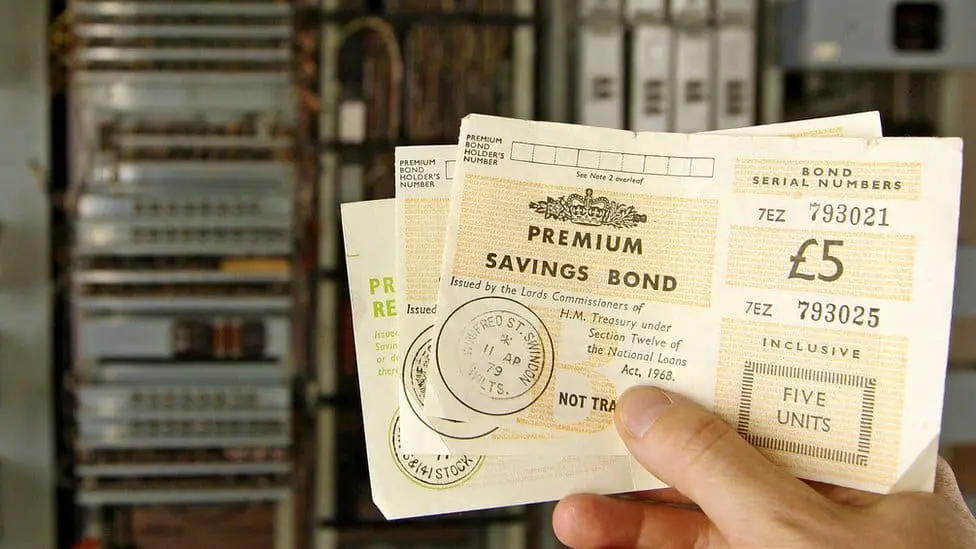
Premium Bonds have had two rate rises in three months. NS&I lifted the prize fund rate from 3.3% to 3.8% for the July 2026 draw, then from 3.8% to 4.35% for the September 2026 draw, with the odds on each £1 Bond shortening to 21,000 to 1. Premium Bonds at 4.35% sit within touching distance of the best savings accounts. Whether they are the better home for your money turns on two things: how the prize money is actually shared out, and what tax you would otherwise pay.
In short
- The Premium Bonds prize fund rate is 4.35% from the September 2026 draw, up from 3.80%, with odds of 21,000 to 1 per £1 Bond.
- That rate is an average across every bond, not a promise. In the September draw about four fifths of the prize money went on £25, £50 and £100 prizes, so a saver who never wins anything bigger can expect roughly 3.5%.
- As at 24 September 2026 the best one-year fixed bonds pay about 5.05%, the best easy-access accounts 4.30% without a bonus, and the best one-year fixed cash ISAs 4.82%.
- Tax is what changes the answer. A higher-rate taxpayer who has used the Personal Savings Allowance keeps 3.03% from a 5.05% fixed bond, below the tax-free 4.35%.
- NS&I’s own Direct ISA still pays 3.80%, so Premium Bonds now carry a higher headline rate than NS&I’s guaranteed tax-free account.
What NS&I announced
NS&I’s press release of 18 August 2026 said holders would “see a boost to the prize fund rate to 4.35%, up from 3.80%, for the September 2026 draw”, with the odds “shortening to 21,000 to 1 from 22,000 to 1”. Every bond gets the new rate automatically. There is nothing to do.
The first draw at the new rate has now run. NS&I’s September results report 6,529,868 tax-free prizes worth £497,086,175, drawn from 137,127,223,215 eligible £1 Bonds, including two £1 million prizes. The minimum holding is still £25 and the maximum £50,000 per person.
How the rate got here
- September 2023: prize fund rate raised to 4.65%, the highest since 1999, as Bank Rate climbed above 5%.
- From 2024: cut in steps as the Bank of England cut Bank Rate from its 5.25% peak.
- April 2026: cut from 3.6% to 3.3%.
- July 2026: raised from 3.3% to 3.8%.
- September 2026: raised from 3.8% to 4.35%.
NS&I rates do not simply follow Bank Rate, which the Bank of England held at 3.75% on 17 September. Each year the Treasury sets NS&I a net financing target, and NS&I raises or cuts its rates to bring in the money it needs. Two rises in quick succession with Bank Rate unchanged suggest it has been short of deposits. By the same logic the rate can move again, without warning, in either direction.
The rest of the NS&I shelf
The August announcement also raised four other products and left the Direct ISA alone.
| NS&I product | Rate as at 24 September 2026 | Tax treatment |
|---|---|---|
| Premium Bonds | 4.35% prize fund rate, from the September draw | Prizes free of income tax and capital gains tax |
| Direct ISA | 3.80% AER, variable (unchanged in August) | Tax-free, uses ISA allowance |
| Junior ISA | 3.70% AER, variable | Tax-free |
| Direct Saver | 3.75% gross/AER, variable, from 18 August | Taxable, counts towards the Personal Savings Allowance |
| Income Bonds | 3.69% gross / 3.75% AER, variable, from 18 August | Taxable, interest paid monthly |
| British Savings Bonds, 1-year Guaranteed Growth | 4.82% gross/AER, fixed, from 18 August | Taxable |
Sources: NS&I press release of 18 August 2026 and NS&I’s product pages, read 24 September 2026. The August release raised British Savings Bonds across every term, with the five-year Guaranteed Growth Bond at 4.85% gross/AER.
Direct ISA and Premium Bonds: the order has flipped
In May both of NS&I’s tax-free flagships paid a headline 3.80%, and the guaranteed Direct ISA was the obvious pick for anyone with ISA allowance to spare. Now Premium Bonds carry 4.35% and the Direct ISA still pays 3.80%. That 0.55 percentage point gap flatters Premium Bonds, because the 4.35% includes the rare large prizes. On the September figures the small prizes alone are worth about 3.5% a year, still below the Direct ISA’s guaranteed 3.80%. Both are backed in full by HM Treasury. The Direct ISA counts against the £20,000 annual ISA allowance; Premium Bonds do not.
The prize fund rate is not a return rate
A 4.35% prize fund rate means that, across the whole pool of bonds, NS&I pays out prizes worth 4.35% of the money invested each year. It does not mean each saver receives 4.35%. Every £1 Bond has the same chance in each draw, so the average return is 4.35% for everyone; what any one person receives depends on which prizes they happen to win.
NS&I’s own September breakdown shows how the money is split. Of the 6,529,868 prizes, 6,446,807, about 98.7%, were £100 or less. Those £25, £50 and £100 prizes added up to about £397.7 million of the £497.1 million paid, roughly 80%. The other 20% went on just over 83,000 prizes of £500 or more, including the two £1 million jackpots.
That gives a rule of thumb. If you never win a prize above £100, your expected return is about four fifths of 4.35%, which is roughly 3.5% a year. The bigger prizes lift the average for the few who win them. The larger the holding, the more prizes it collects and the closer its result tends to sit to the average. The smaller the holding, the more the year depends on luck.
| Holding | Prizes you can expect a year, on average | Average return at 4.35% | Expected from £25 to £100 prizes alone |
|---|---|---|---|
| £1,000 | About 0.6, so roughly one prize every 21 months | £43.50 | About £35 |
| £10,000 | About 6 | £435 | About £348 |
| £50,000 | About 29 | £2,175 | About £1,740 |
Worked from the odds of 21,000 to 1 per £1 Bond and twelve draws a year, and from the September 2026 prize breakdown. These are averages; a real year can land well above or below them.
How Premium Bonds compare as at 24 September 2026
Best-buy rates change weekly, so treat these as a snapshot. All figures are from Moneyfacts unless stated, read on 23 and 24 September 2026.
| Account | Best rate | Notes |
|---|---|---|
| Premium Bonds | 4.35% prize fund rate | Tax-free; about 3.5% from small prizes alone |
| Easy-access savings, no bonus | 4.30% AER | Progressive Building Society and Tipton & Coseley Building Society |
| Easy-access savings, with a bonus | 5.00% AER | LemFi, including a 1.89% bonus for six months |
| One-year fixed bond | 5.05% AER | GB Bank; Kent Reliance pays 5.06% on a 13-month bond |
| One-year fixed cash ISA | 4.82% AER | Close Brothers Savings and OakNorth Bank |
| Easy-access cash ISA | 4.87% AER | eToro, including a 1% boost paid after 12 months (Be Clever With Your Cash, 23 September) |
| NS&I Direct ISA | 3.80% AER | Tax-free, 100% Treasury backed |
The big banks’ own easy-access accounts pay far less. Moneyfacts found on 17 September that some of the most flexible accounts from the big banks “pay just 1.16% on average”.
Against easy-access savings
Before tax, the best easy-access account without a bonus pays 4.30%, a hair below the 4.35% prize rate and well above the 3.5% a saver can expect from small prizes alone. The 5.00% headline accounts carry introductory bonuses that fall away after six or twelve months. Easy-access interest is guaranteed on every pound. Premium Bonds are just as easy to get out of, with no penalty for cashing in.
Against fixed-rate savings
A one-year fixed bond at 5.05% beats the 4.35% prize rate before tax, and guarantees it. The price is access: the money is locked away for the term, and many fixed bonds allow no withdrawals before it ends. Premium Bonds can be cashed in at any time.
Against cash ISAs
Cash ISAs are the closest like-for-like, since both are free of tax whatever your band. The best one-year fixed cash ISA at 4.82% beats the Premium Bonds prize rate and is guaranteed. The ISA route is capped by the £20,000 annual allowance, which falls to £12,000 for cash ISAs for under-65s from 6 April 2027 (see our Cash ISA cap 2027 guide). Premium Bonds sit outside the ISA allowance, which makes them one of the few tax-free homes left once it is used up.
Where tax changes the answer
Premium Bond prizes are free of income tax and capital gains tax, and they do not use up your Personal Savings Allowance. That allowance lets a basic-rate taxpayer earn £1,000 of interest a year tax-free and a higher-rate taxpayer £500; additional-rate taxpayers get nothing. Once it is used, every extra pound of interest is taxed at your rate.
| Taxpayer, allowance used up | One-year fix at 5.05%, after tax | Easy access at 4.30%, after tax | Premium Bonds |
|---|---|---|---|
| Basic rate (20%) | 4.04% | 3.44% | 4.35% average, about 3.5% from small prizes |
| Higher rate (40%) | 3.03% | 2.58% | 4.35% average, about 3.5% from small prizes |
| Additional rate (45%) | 2.78% | 2.37% | 4.35% average, about 3.5% from small prizes |
For a higher or additional-rate taxpayer whose allowance is used and whose ISA allowance is full, Premium Bonds now come out ahead even on the small-prize figure. For a basic-rate taxpayer still inside the £1,000 allowance, no tax is due on ordinary interest, so the tax-free feature is worth nothing and the guaranteed accounts win.
Who is better off with Premium Bonds at 4.35%
- Higher and additional-rate taxpayers who have used their Personal Savings Allowance and their ISA allowance, for the reasons in the table above.
- Savers who want 100% Treasury backing on up to £50,000 without spreading money across banks. The Financial Services Compensation Scheme protects £120,000 per person at each banking licence, which covers most balances at a single bank.
- Savers who enjoy the draw and accept that most years they will earn less than the headline rate, in return for a small chance of a large prize.
Who is probably better off elsewhere
- Basic-rate taxpayers inside their £1,000 allowance, who pay no tax on ordinary interest and can get a guaranteed 4.30% easy access or 5.05% fixed.
- Savers with ISA allowance to spare, where a 4.82% fixed cash ISA is tax-free and guaranteed.
- Small holdings, where a year can easily pass with one prize or none, so the result is more a matter of luck than of rate.
Practical mechanics
- Buying: online at nsandi.com, by phone or by post, from £25 up to £50,000 per person. A bond enters the draw once it has been held for a whole calendar month after the month it was bought, so a bond bought in September is first in the November draw.
- Holding: no fees and nothing to do. Bonds stay in every monthly draw until you cash them in.
- Cashing in: online, by phone or by post, at any time and with no penalty. The money goes to your nominated bank account.
- Prizes: paid to your nominated bank account, or reinvested in more bonds if you choose, up to the £50,000 limit.
FAQ
Is the 4.35% rate guaranteed?
No. 4.35% is the prize fund rate: the share of all bonds in issue that NS&I pays out as prizes over a year, on average. Individual results depend on which prizes you win. NS&I can change the rate, and it has changed it twice since July.
Do I need to do anything to get the new rate?
No. Every eligible bond is entered into each monthly draw at the prize fund rate in force at the time.
Are Premium Bond prizes taxable?
No. NS&I states that prizes are free from UK income tax and capital gains tax, and they do not count towards your Personal Savings Allowance.
What would £50,000 in Premium Bonds earn?
On average about £2,175 a year at 4.35%, from around 29 prizes. About £1,740 of that comes, on average, from £25, £50 and £100 prizes, and the rest from the chance of larger ones, so a typical year lands somewhere between the two and some years well above or below.
Are Premium Bonds a form of gambling?
They are not classed as gambling under UK law, and your capital is never at risk: you can always cash in what you put in. But the return is decided by chance. For most savers the practical difference is small. For anyone inclined to overestimate their odds of a big win, the small-prize figure of about 3.5% is the more honest expectation.
Is the £50,000 limit per account or per person?
Per person. Children can hold Premium Bonds too, with a parent or guardian looking after them, and each child has their own £50,000 limit.
The Savvy Investor’s take
At 4.35% Premium Bonds are the most competitive they have been since the rate cuts began, and for one group they now win outright: higher and additional-rate taxpayers who have used both their savings allowance and their ISA allowance. For them, even the small-prize figure of about 3.5% beats what a 5.05% fixed bond leaves after tax.
For everyone else the headline flatters the product. About four fifths of the prize money goes out in £25 to £100 prizes, so the realistic expectation is nearer 3.5% than 4.35%, and guaranteed accounts at 4.30% easy access, 4.82% in a fixed cash ISA and 5.05% in a fixed bond all pay more with no luck involved. NS&I has moved this rate three times in six months, so it is worth checking again before relying on it.
Information, not advice. This article describes the Premium Bonds prize fund rate and compares it with other savings options as at 24 September 2026. It does not take account of any reader’s personal circumstances and is not regulated financial advice. Savvy Investor Guide is not authorised or regulated by the Financial Conduct Authority. Rates quoted are current at the time of writing and change often. For free, government-backed guidance, contact MoneyHelper.
Key sources
- NS&I, press release PR260818, 18 August 2026.
- NS&I, September 2026 prize draw results, 1 September 2026.
- NS&I: Premium Bonds, Direct ISA and Direct Saver product pages, read 24 September 2026.
- Bank of England, Monetary Policy Summary, September 2026.
- Moneyfacts, easy-access savings, one-year fixed bonds and one-year fixed ISAs, read 24 September 2026.
- Moneyfacts, big-bank easy-access rates, 17 September 2026.
- Be Clever With Your Cash, best cash ISAs, updated 23 September 2026.
- GOV.UK, tax on savings interest.
- Savvy Investor Guide: Cash ISA Cap 2027: the £12,000 under-65 saver’s guide.
Update history: 24 September back to 2 July 2026
Update, 24 September 2026. The article has been rewritten for the 4.35% rate. The earlier version was written in May against the 3.80% rate and compared it with savings rates of the time, around 4.51% for easy access and 4.6% for one-year fixes; the entries below then asked readers to substitute the new rate. The body now uses 4.35% throughout and every comparison was re-run against rates read on 23 and 24 September 2026. It also adds, from NS&I’s September draw figures, how much of the prize money is paid in small prizes, and it notes that NS&I’s Direct ISA stayed at 3.80% in August, so the two tax-free products no longer match.
Update, 5 September 2026. The September draw has run, so 4.35% is now the rate in effect rather than the rate coming. NS&I’s draw release of 1 September reports that “In the September draw, 6,529,868 tax-free prizes will be paid to Premium Bonds prize draw winners totalling £497,086,175”, from 137,127,223,215 eligible £1 Bonds, and names two £1 million jackpot winners, in Norwich and London. The prize fund rate is 4.35% and the odds are 21,000 to 1 for every £1 Bond.
Read everything below with that substitution in mind. The article was written against the 3.80% rate that took effect with the July 2026 draw, and compares it with easy-access savings of around 4.51%. The structure of the comparison holds and the arithmetic is unchanged; only the Premium Bonds input has moved, by 55 basis points. At 4.35% the tax-free case strengthens for anyone who has already used their Personal Savings Allowance, and it narrows the gap to the guaranteed alternatives rather than closing it.
The September breakdown also shows, in NS&I’s own numbers, why the headline rate is not what a typical holder receives. Of the 6,529,868 prizes, two were £1 million and 95 were £100,000, while 6,446,807, about 98.7%, were £100 or less. That skew is what pulls the average above the median outcome, and it does not shrink as the rate rises. Source: NS&I, 1 September 2026.
Update, 20 August 2026. NS&I has raised the Premium Bonds prize fund rate again. Its press release of 18 August 2026 confirms the rate moves from 3.80% to 4.35% tax-free from the September 2026 draw, the odds improve from 22,000 to 1 to 21,000 to 1 for every £1 Bond, and around 308,000 extra prizes join the draw.
The headline now carries the new rate; the article below does not. The article below weighs a 3.80% prize fund rate against taxed savings, and concludes the answer turns largely on whether you have used your Personal Savings Allowance. At 4.35% the tax-free comparison strengthens across the board. The arithmetic in the sections below is unchanged; only the input has moved, so read the worked examples with the new rate substituted.
One caution from the analysis below carries over, and it gets more important as the advertised rate rises, not less. A prize fund rate is an average across a prize distribution, not an interest rate, and it is not what a typical holder receives. For a modest holding the median outcome stays well below the headline figure, and that gap widens as the rate goes up.
Update, 2 July 2026. The 3.8% prize fund rate is now live, effective from the July 2026 prize draw (July winners can be checked from 2 July). The slightly improved odds of 1-in-22,000 also take effect. The comparison in this guide still holds, and if anything it has widened: the best easy-access savings now pay around 5%, up from the 4.51% cited below, so a guaranteed easy-access rate stays comfortably above the Premium Bonds prize fund rate. Premium Bonds remain a tax-free gamble rather than a rate play.