Retirement Planning
-
FCA Targeted Support 2026: Your Pension Platform Can Now Nudge You, and What That Means
Read more: FCA Targeted Support 2026: Your Pension Platform Can Now Nudge You, and What That MeansThe FCA’s new targeted support regime is live from 6 April 2026. What it lets pension platforms do, what it doesn’t replace, and how to use it as a UK saver.
-
Americans are also losing the retirement-savings argument: what the 2026 EBRI Retirement Confidence Survey says
Read more: Americans are also losing the retirement-savings argument: what the 2026 EBRI Retirement Confidence Survey saysEBRI’s 2026 Retirement Confidence Survey found 64% of Americans confident about retirement, the lowest reading since 2017. Workers expect to retire at 70 at four times the rate retirees actually do. We unpack the data, the Fidelity overlay showing that plan ownership more than doubles confidence, and the practical response.
-
OBBBA permanently raised the federal estate exemption to $15M: US estate planning after the July 2025 law
Read more: OBBBA permanently raised the federal estate exemption to $15M: US estate planning after the July 2025 lawThe One Big Beautiful Bill Act (July 2025) permanently raised the US federal estate and gift tax exemption to $15 million per person, or $30 million per married couple, with no sunset. State estate tax in roughly 12 jurisdictions still bites. Here is what changed, who benefits most, and where planning work still matters in…
-
I-bonds rise to 4.26% for May-October 2026: the US sibling to UK Premium Bonds
Read more: I-bonds rise to 4.26% for May-October 2026: the US sibling to UK Premium BondsThe US Treasury raised the Series I Savings Bond composite rate to 4.26% for the May to October 2026 window, with the fixed-rate component holding at 0.90% locked for the bond’s 30-year life. We compare I-bonds against the best high-yield savings accounts, CDs, T-bills and TIPS, and set out who actually benefits at the current…
-
Pension Inheritance Tax 2027: UK Estate Planning Guide
Read more: Pension Inheritance Tax 2027: UK Estate Planning GuideFrom 6 April 2027, unspent UK pension pots fall into the IHT estate. What’s changing, who’s hit hardest, and the 6 planning moves to consider before the 2027 deadline.
-
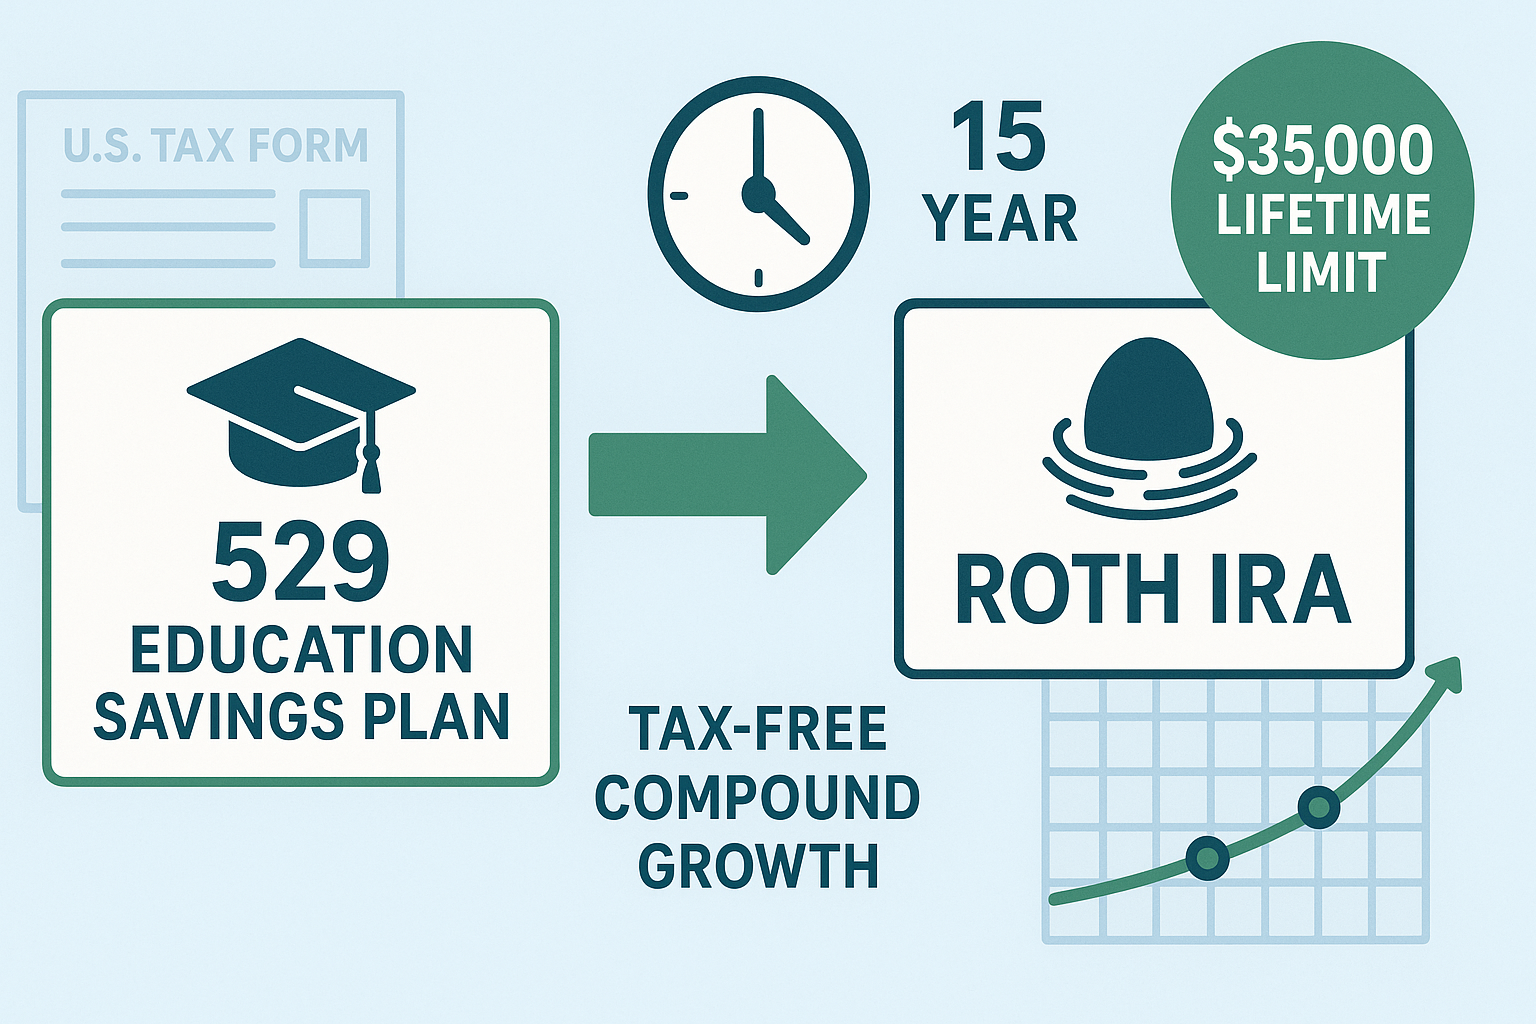
529 to Roth IRA Rollover: Complete SECURE 2.0 Guide for 2026
Read more: 529 to Roth IRA Rollover: Complete SECURE 2.0 Guide for 2026Run the 529-to-Roth IRA rollover cleanly in 2026: the 15-year rule, $35,000 lifetime cap, $7,500 annual limit, the state-tax traps that catch people, and step-by-step execution.
-
FIRE Movement: The Complete 2026 Guide to Financial Independence and Early Retirement
Read more: FIRE Movement: The Complete 2026 Guide to Financial Independence and Early RetirementFIRE planning in 2026: the ACA subsidy cliff is back, Morningstar lifted the safe withdrawal rate to 3.9%, and the IRS pushed limits higher. FI number, healthcare bridge, Roth conversion ladder, and five interactive calculators.
-

The Complete 401(k) Optimization Playbook for 2026
Read more: The Complete 401(k) Optimization Playbook for 2026Optimize your 401(k) for 2026: contribution limits up to $35,750 for ages 60-63, the mega backdoor Roth at $72,000, the Traditional-versus-Roth call, expense ratios, the new mandatory Roth catch-up for $150K+ earners, plus how to spot a bad plan and what to do at job changes. Built to add six figures to lifetime retirement savings.
-

Backdoor Roth IRA: Step-by-Step Guide (2026)
Read more: Backdoor Roth IRA: Step-by-Step Guide (2026)Income too high for a direct Roth IRA? The backdoor Roth opens the door for high earners at $7,500 a year in 2026 ($8,600 if you’re 50+). This guide walks Fidelity, Vanguard and Schwab step-by-step, runs the pro-rata math, and breaks down Form 8606 line by line.
-

Solo 401(k) Complete Guide for Self-Employed Workers (2026)
Read more: Solo 401(k) Complete Guide for Self-Employed Workers (2026)A Solo 401(k) lets the self-employed contribute up to $72,000 in 2026 ($80,000 if you’re 50+, $83,250 if you’re 60-63), well past what SEP IRAs and SIMPLE IRAs allow. This guide covers eligibility, providers, setup, contribution strategy, mega backdoor Roth, and the SECURE 2.0 Roth catch-up rule with the sole-proprietor carve-out most coverage misses.
Subscribe
Sign up with your email address to receive our weekly news
Latest news
- UK house prices in October 2026: five indices, five different answers
- How to file a CFPB complaint in 2026, and what it can still achieve
- SEC Regulation Crypto Assets: what the proposed rules would mean for investors
- New government and your money: what has changed since July, and what has not
- Triple lock 2030: what changes for the State Pension, and what does not
Categories
- Backdoor Roth (1)
- Cryptocurrency (5)
- Expat Living & Lifestyle (1)
- General Blog (22)
- Index Funds (1)
- Investing Basics (6)
- Investment Guides (6)
- Investment Platforms (1)
- Investment Strategies (16)
- Investments (2)
- IRAs & Tax-Advantaged Accounts (13)
- ISAs and Pensions (7)
- Property Investment (8)
- Real Estate Investing (4)
- Retirement Planning (36)
- Tax Strategy (26)
- Tax-Efficient Investing (8)
- UK Investing (63)
- UK Property Investment (6)